
Three ways to finance your business
Working capital
Cover payroll, inventory, and seasonal cash flow gaps with a flexible line of credit.
Equipment financing
Finance machinery, vehicles, or technology, with the equipment itself as collateral.
Commercial and industrial loans
Fund expansion, refinancing, or general business needs with a term loan sized to your project.
Meet the team
Accordia Bank’s dedicated lending experts look out for your business.
Loan Officers
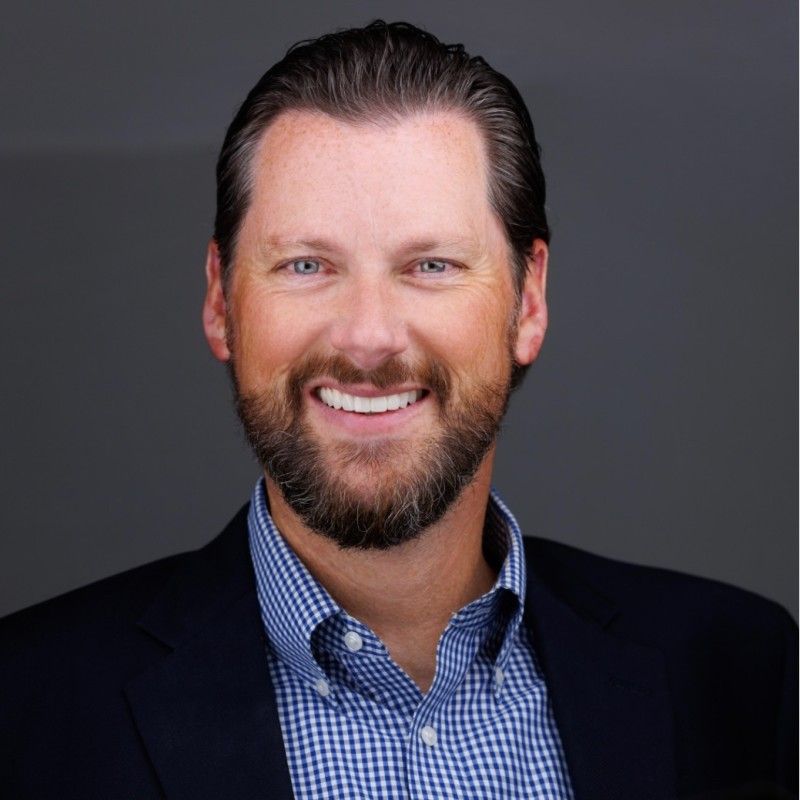
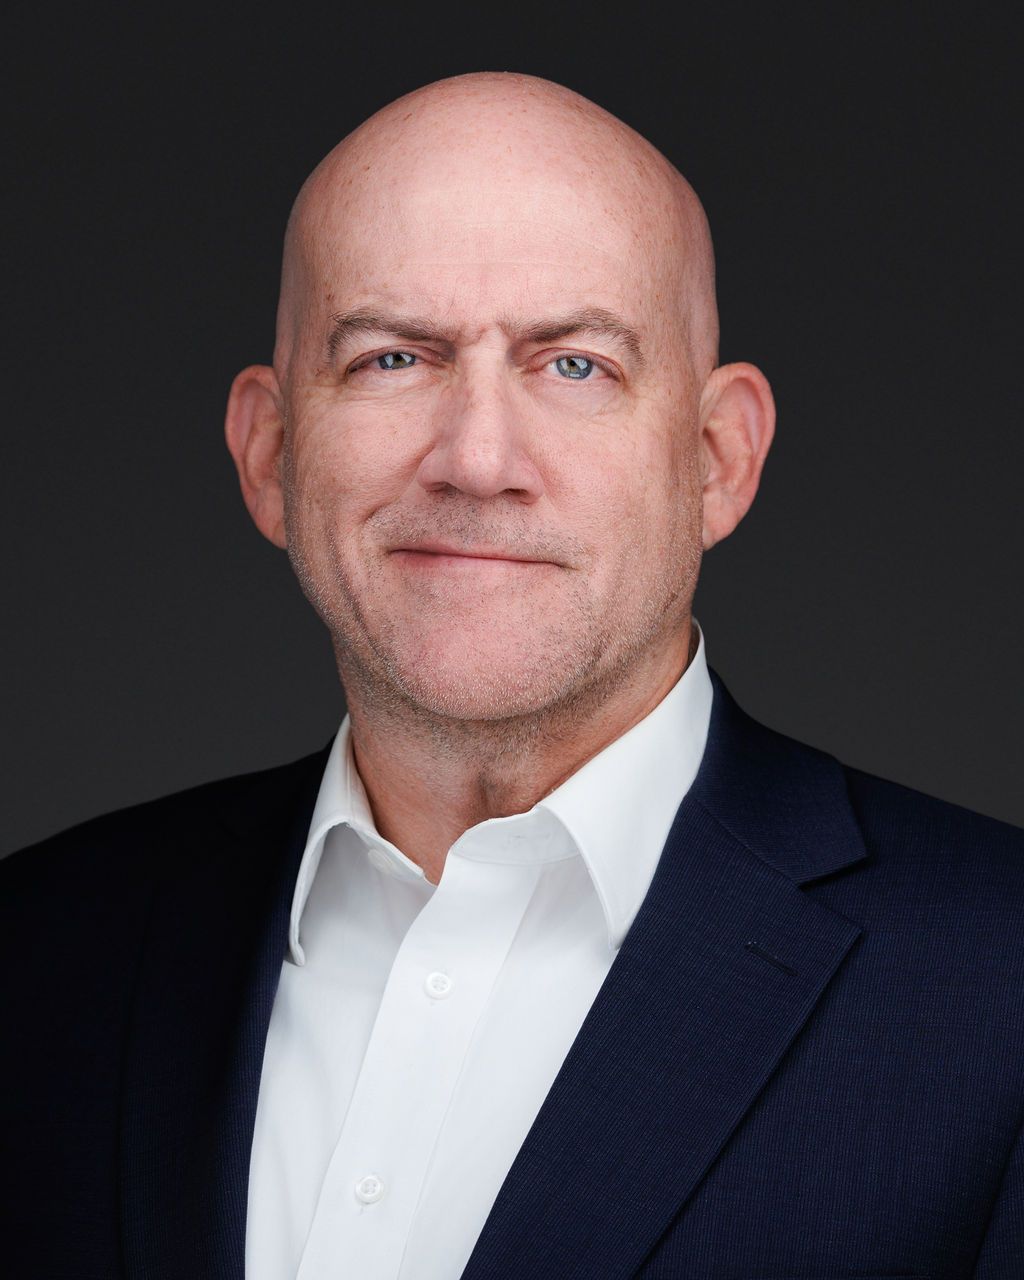
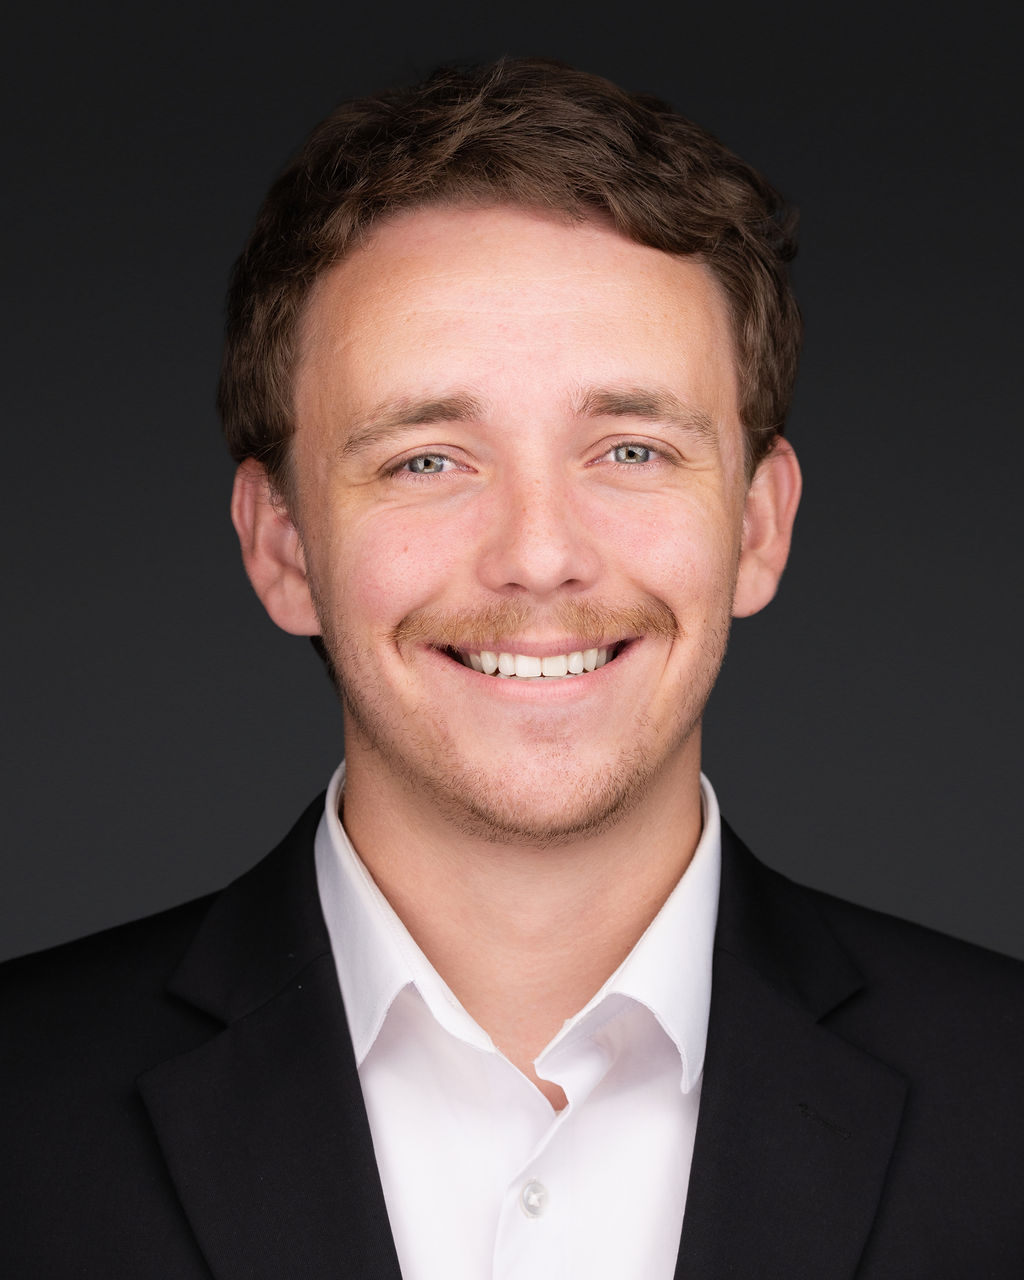
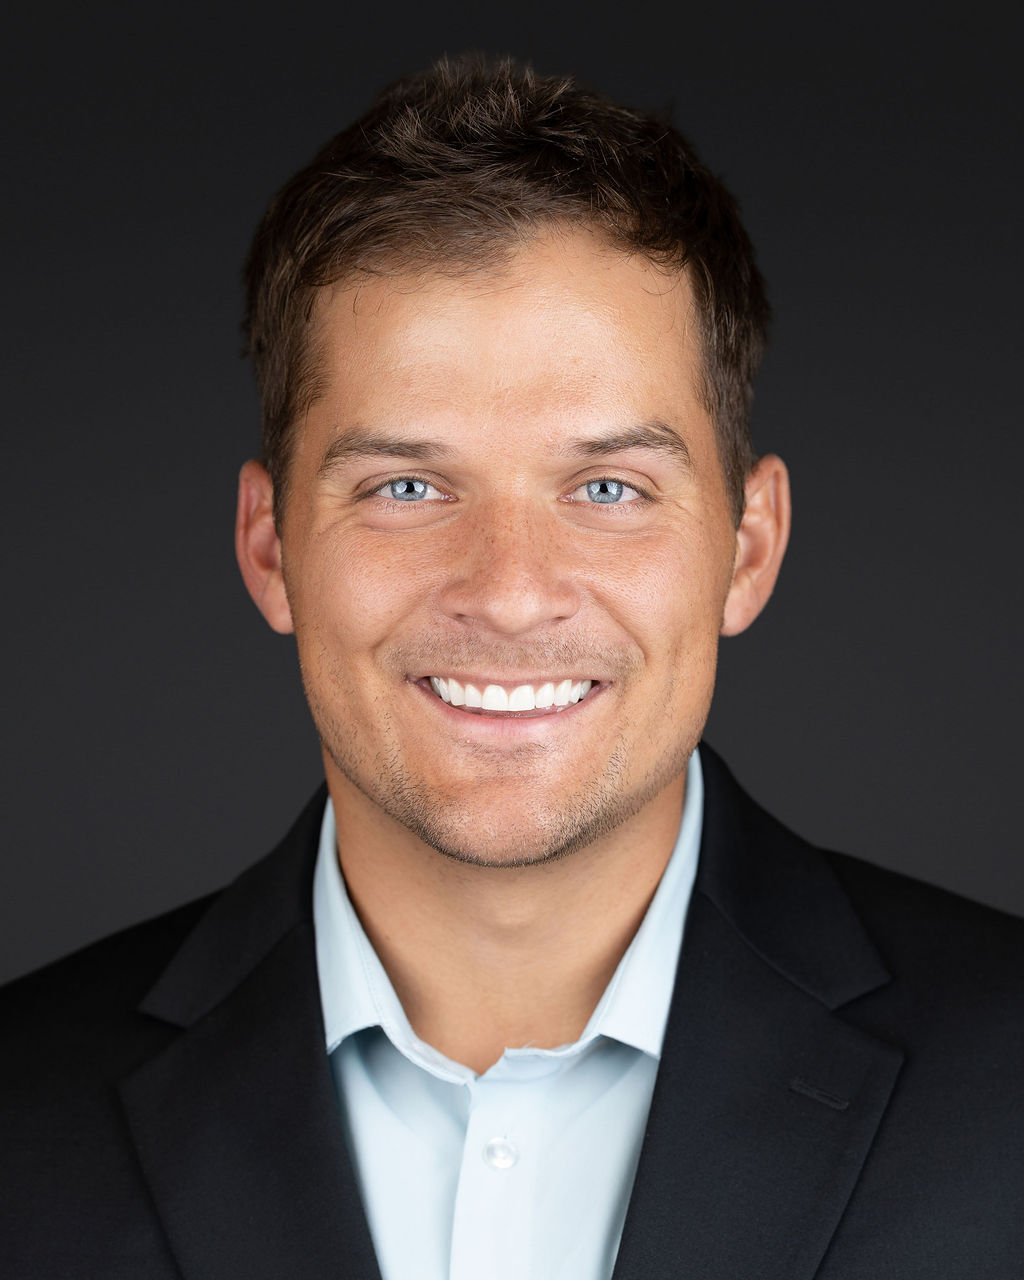
SBA Team
Agriculture Lending Team
Business loan types at a glance
| Loan type | Best for | Typical term | Collateral |
|---|---|---|---|
| Working capital loan or line of credit | Payroll, inventory, seasonal cash flow gaps | Revolving or 1 to 2 years | Often unsecured or backed by receivables |
| Equipment financing | Purchasing machinery, vehicles, or technology | Matches the equipment's useful life, often 3 to 7 years | The equipment itself |
| Commercial and industrial loan | Expansion, refinancing, general business purposes | 3 to 10 years, sometimes longer | Business assets, cash flow, or a blanket lien |
Estimate your payments
Grow your business on your terms
Get streamlined decisions from lenders who understand the Utah market and move at your pace.
Build your dream business
Fund your new building with flexible financing and competitive rates.
A nationwide SBA-preferred lender
Get funding to grow your business from a local team that understands your needs.
Your ag lender
Access lending for farms, ranches, and rural businesses.
Cash when you need it
Access flexible funds for day-to-day expenses, whenever they come up.
Power your business forward
Get financing for equipment, inventory, or growth, tailored to your business needs.
Frequently Asked Questions
-
Working capital loans fund day to day operating costs like payroll, inventory, and short term cash flow gaps. Equipment financing is tied to a specific asset, uses the equipment itself as collateral, and is repaid over the useful life of that equipment.
-
A commercial and industrial loan, often called a C&I loan, is a business purpose loan issued to a company rather than secured against real estate. Utah banks use C&I loans to fund general business needs such as expansion, equipment, or working capital, typically underwritten against business cash flow and creditworthiness.
-
Utah banks generally review time in business, annual revenue, personal and business credit history, existing debt obligations, and available collateral. Newer businesses often need a stronger personal credit profile or a co-signer, while established businesses can qualify based primarily on cash flow and revenue trends.
-
Startups can qualify for financing in Utah, though options are narrower than for established businesses. Common paths include SBA backed loans, equipment financing tied to a purchased asset, and lines of credit that rely on the owner's personal credit and a solid business plan.
-
Business expansion is usually funded with a term loan or a commercial and industrial loan sized to the total project cost, including renovation, new locations, or hiring. Businesses expecting ongoing, variable costs during expansion often pair a term loan with a working capital line of credit.